Bloomberg:
Trading of credit-default swaps insuring U.S. Treasuries has doubled as the government struggles to agree on plans to cut its budget deficitand raise the $14.3 trillion national debt limit.
A total of 819 contracts covering a net notional $4 billion of debt were outstanding as of May 20, up from 449 contracts covering $2 billion a year ago, according to the Depository Trust & Clearing Corp. Average daily trading volume surged to $490 million last week from $10 million the week before, making the U.S. the fourth most active among 1,000 contracts tracked by DTCC, up from 633rd.
Swaps insuring Treasuries for five years are trading at 50 basis points, according to CMA. That compares with 37 basis points in April and a record 100 basis points at the peak of the financial crisis in 2009. One-year contracts are now more expensive than Panama, the Philippines and Mexico, CMA prices show.
Anyone else see the humor here?

This is my effort to help fit the pieces together to get a better picture of the capital markets.
“It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so.”
Showing posts with label Treasuries. Show all posts
Showing posts with label Treasuries. Show all posts
Thursday, May 26, 2011

Wednesday, March 16, 2011
Tuesday Fixed Income Brief
Interesting day today to say the least. Risk came off in torrential form as Asia got pounded and Europe followed suit. What I see as the primary sources of risk right now:


- A total meltdown at one or more reactor in Fukushima. The typhoon has already constrained capacity - which will no doubt be felt by nearly all manufacturers, but a total meltdown will shutter more factories and further reduce capacity. The hit will obviously be felt more in Japan, but the global markets will roll. As I am aware as of this writing, it does not look likely, but cracks in the containment units and hydrogen build-up can go bad fast.
- Continued - and increasing - unrest in the middle east. With the Saudis in Bahrain, Iran will be pressed to react in some way - either in Bahrain or opening up a new front somewhere else to spread Saudi (and/or coalition) forces thin. The Saudis are also facing discontent at home, but this move helps keep an opposition movement down with the show of force. Japan of course has averted the worlds eye from the middle east for the time being.
I am also concerned about the effect of the European Financial Stability Facility ( euro440 billion - $606 billion) which allows it to buy government bonds (from the governments if austerity measures are agreed to) instead of on the secondary markets - which means the ECB is still the buyer of last resort.
With that said, lets look at some fixed income:
Treasuries obviously had a good day as risk came off the books.

Corporates were mixed, but hi/low ratio for IG and HY continued to be strong:

Quack, quack AFLAC (75% sales as a % of 2010 revenue from Japan) was a solid 50 bps wider - and fired Gilbert Gottfried. Other bank/finance names out 7-10bps. EXC, SO, PCG and EIX feeling pressure due to concerns about effect on nuclear power (Germany is taking 7 older units down for inspection over the next few months).
Oh yeah, lets not forget that Moody's pinged Portugal from A1 to A3: "The cost of market funding is likely to remain high until the deficit has been reduced to a sustainable level and the prospects for economic growth have improved," it said in a statement.
Kinda tired, gonna close with that.
Tuesday, December 14, 2010
Treasury Blood Letting
Anyone get the tag of that truck that hit Treasuries?
Treasuries continue their sell-off today as we are getting signs that a recovery is in our midst (yep, them green shoots). I fully expect that this will continue to happen should we continue to trade off fundamental data. Should the Eurozone blossom into a full fledged panic, all bets are off. I would stay short my duration here and focus on spread product, well credit product. Why credit product - mortgage duration is extending and credit still has a favorable risk/return profile. The risk premium in credit is still attractive relative to historical standards. More on this later.

Disclosure: Long TBT.
Treasuries continue their sell-off today as we are getting signs that a recovery is in our midst (yep, them green shoots). I fully expect that this will continue to happen should we continue to trade off fundamental data. Should the Eurozone blossom into a full fledged panic, all bets are off. I would stay short my duration here and focus on spread product, well credit product. Why credit product - mortgage duration is extending and credit still has a favorable risk/return profile. The risk premium in credit is still attractive relative to historical standards. More on this later.

Disclosure: Long TBT.
Monday, December 13, 2010
Treasuries: Reality Time?
How to lose NRSRO status post haste:
Moody's warned on Monday that it could move a step closer to cutting the U.S. Aaa rating if President Barack Obama's tax and unemployment benefit package becomes law.
The plan agreed to by President Barack Obama and Republican leaders last week could push up debt levels, increasing the likelihood of a negative outlook on the United States rating in the coming two years, the ratings agency said.
A negative outlook, if adopted, would make a rating cut more likely over the following 12-to-18 months.
For the United States, a loss of the top Aaa rating, reduce the appeal of U.S. Treasuries, which currently rank as among the world's safest investments.
"From a credit perspective, the negative effects on government finance are likely to outweigh the positive effects of higher economic growth," Moody's analyst Steven Hess said in a report sent late on Sunday.
Monday, November 29, 2010
Bailout Jitters Favor Long Duration
Anyone else notice that the new "bailout disappointment" is showing the 10yr T no love? Its been about getting long.

So much for the QE "preferred habitat" theory. Everything is out the window when fear comes a knocking.

So much for the QE "preferred habitat" theory. Everything is out the window when fear comes a knocking.
Wednesday, November 3, 2010
John Mauldin - great quote
Great quote from John Mauldin:
We would avoid Treasuries at all costs. Lending to our government at 2.6 percent for 10 years is a great way to become a millionaire - if you’re already a billionaire. Sooner or later, everything being earned on the upside of this liquidity-induced rally will be given back in spades – the only question is when.
QE2 - As expected, BUY belly SELL long end
QE2 - Buy the belly, sell long end
On November 3, 2010, the Federal Open Market Committee (FOMC) decided to expand the Federal Reserve’s holdings of securities in the System Open Market Account (SOMA) to promote a stronger pace of economic recovery and to help ensure that inflation, over time, is at levels consistent with its mandate. In particular, the FOMC directed the Open Market Trading Desk (the Desk) at the Federal Reserve Bank of New York to purchase an additional $600 billion of longer-term Treasury securities by the end of the second quarter of 2011.
The FOMC also directed the Desk to continue to reinvest principal payments from agency debt and agency mortgage-backed securities into longer-term Treasury securities. Based on current estimates, the Desk expects to reinvest $250 billion to $300 billions over the same period, though the realized amount of reinvestment will depend on the evolution of actual principal payments.
Taken together, the Desk anticipates conducting $850 billion to $900 billion of purchases of longer-term Treasury securities through the end of the second quarter. This would result in an average purchase pace of roughly $110 billion per month, representing about $75 billion per month associated with additional purchases and roughly $35 billion per month associated with reinvestment purchases.
The Desk plans to distribute these purchases across the following eight maturity sectors based on the approximate weights below:
Nominal Coupon Securities by Maturity Range* TIPS**
Nominal Coupon Securities by Maturity Range*
TIPS**
1.5-2.5 2.5-4 4-5.5 5.5-7 7-10 10-17 17-30 1.5-30
Years Years Years Years Years Years Years Years
5% 20% 20% 23% 23% 2% 4% 3%
*The on-the-run 7-year note will be considered part of the 5½- to 7-year sector, and the on-the-run 10-year note will be considered part of the 7- to 10-year sector.
On November 3, 2010, the Federal Open Market Committee (FOMC) decided to expand the Federal Reserve’s holdings of securities in the System Open Market Account (SOMA) to promote a stronger pace of economic recovery and to help ensure that inflation, over time, is at levels consistent with its mandate. In particular, the FOMC directed the Open Market Trading Desk (the Desk) at the Federal Reserve Bank of New York to purchase an additional $600 billion of longer-term Treasury securities by the end of the second quarter of 2011.
The FOMC also directed the Desk to continue to reinvest principal payments from agency debt and agency mortgage-backed securities into longer-term Treasury securities. Based on current estimates, the Desk expects to reinvest $250 billion to $300 billions over the same period, though the realized amount of reinvestment will depend on the evolution of actual principal payments.
Taken together, the Desk anticipates conducting $850 billion to $900 billion of purchases of longer-term Treasury securities through the end of the second quarter. This would result in an average purchase pace of roughly $110 billion per month, representing about $75 billion per month associated with additional purchases and roughly $35 billion per month associated with reinvestment purchases.
The Desk plans to distribute these purchases across the following eight maturity sectors based on the approximate weights below:
Nominal Coupon Securities by Maturity Range* TIPS**
Nominal Coupon Securities by Maturity Range*
TIPS**
1.5-2.5 2.5-4 4-5.5 5.5-7 7-10 10-17 17-30 1.5-30
Years Years Years Years Years Years Years Years
5% 20% 20% 23% 23% 2% 4% 3%
*The on-the-run 7-year note will be considered part of the 5½- to 7-year sector, and the on-the-run 10-year note will be considered part of the 7- to 10-year sector.
Wednesday, October 27, 2010
Treasuries - Yes, There Will be Blood
Govvies getting whacked as QE2 becomes QE2 lite. You know the market is on shaky ground when everyone is relying on the Fed to support their positions. Since QE2 lite rumors started surfacing, this is what we have seen:

Ouch.
The 10 year:
 Oh boy, look out below!
How about the curve:
 Belly gets whacked going through auctions.
Get shorty:

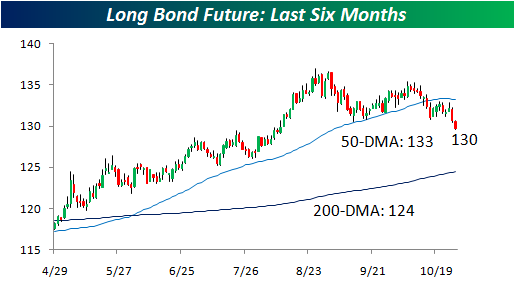
Ouch.
The 10 year:

How about the curve:

Get shorty:

Thursday, October 21, 2010
Week ahead for US Debt
Week ahead for Govvies:
Monday: $29 billion in 13-week bills and $28 billion in 26-week bills;
Tuesday: $35 billion in two-year notes (same as last month)
Wednesday: $35 billion in five-year notes (same as last month)
Thursday: $29 billion in seven-year notes (same as last month)
Friday: and on the fifth day, the Treasury took a rest - and it was good (more time for POMO).
Will trade for rare earth.
Monday: $29 billion in 13-week bills and $28 billion in 26-week bills;
Tuesday: $35 billion in two-year notes (same as last month)
Wednesday: $35 billion in five-year notes (same as last month)
Thursday: $29 billion in seven-year notes (same as last month)
Friday: and on the fifth day, the Treasury took a rest - and it was good (more time for POMO).
Will trade for rare earth.
Subscribe to:
Posts (Atom)